
Disclosure: Everything here is educational content and nothing is Financial advice.
I have peppered this article with short videos to help you understand clearly.
In this article I dove deeper with Samuel Dean , A molecular and cell biology professor from University of Warwick, UK to help me cover this industry
Lets get a little intro to the Drug discovery problem before we can understand what does he mean with AI native companies and processes
There is a lot of promise and hype in Pharma/healthcare and AI, we try to separate the marketing vs. reality together
PROBLEM: 10–15 years to get one drug from idea to pharmacy shelf. ~$2.6B per approved drug. with 99% of screened compound do not even reach humans
The whole system was built to say no.
Make thousands of compounds. Throw them at a target. Watch almost all of them do nothing, or kill the cell. Move the few survivors into animals. Then into humans. Watch most of those die too.
It’s the world’s most expensive bouncer: turns away 9,999 people to let one in — and charges full price for every rejection at the door.
Big Pharma built the only factory on Earth whose main product is no. Only Berghain comes close.
The number of possible small molecules sits around 10 to the power of 60 (Essentially infinite)— a combination lock so long that guessing one click per second outlasts the age of the universe.
And chemists were doing exactly that. Turning the dial by hand, a few thousand tries per program, hoping to hit the code.
AI models do it completely differently. They study the shape of chemical space, predict which corners of it stick to a target, and then write molecules that never existed in nature — tuned for blood-brain-barrier crossing, oral absorption and low toxicity all at the same time.
Allright lets jump into the important insights
INSIGHT 1
Molecules vs. Antibody drugs
Antibodies are another important class of drugs that go through the same process and are very important for certain types of diseases.
However, they are big molecules
And big means they can’t get everywhere.
Throw a great antibody at a tumour and it strips the outer layers — but it can’t reach the center. It’s a size problem, not a toxicity problem.
If you can’t get there, you cannot fix it
Small molecules are tiny and precise. They reach the center of the tumor.
Second point, the chemical space is effectively infinite — there are no running out of new molecules to design. Ever.
If you had to master one drug class, you’d pick small molecules.
Antibodies have their own advantages like having less toxicity or off targets effects. ABCL focuses on antibodies
Lets tackle it later
INSIGHT 2
No AI-discovered drug has FDA approval YET.
The furthest any have progressed is Phase 2. That’s a useful sobriety check against the drug discovery-side hype — the sector is still in “prove it,” not “proven.” phase
INSIGHT 3
The model is basically free now — testing is the bottleneck
The AlphaFold (AF) jump was architectural, not just “more data.”
AF1/2 leaned on training-set correlation (co-evolving amino acids, deep sequence alignments).
AF3 is diffusion-based — it reconstructs 3D structure from a randomized atom cloud the way a language model predicts the next token, and this keys into the actual mechanism of folding rather than memorized pattern-matching.
That’s why it works on inputs/proteins “it’s got no right to work on.” Things that aren’t in the training set at all. It’s a step change. Woah seriously what? This single unlock is arguably what re-rated the whole sector.
So every bro who told us AI can only regurgitate yesterday's knowledge can sit down.
Here is a video with the explanation
Pay Attention to Sam’s last sentence. AF3 is not limited to proteins, it can be extended to small molecules, nucleotides like RNA etc.
Now, what the ramifications of AF3 is that it allows you to have in Silico screens (Screening for hundreds of thousands of potential candidates on your laptop) and arrive at a suitable candidate quicker
INSIGHT 4
The winning architecture is a closed loop, not a smarter model.
Propose in Silico (Your laptop) → then test in an automated wet lab → feed results back → redesign.
Sam is explicit that this loop — tight, fast, ideally robotic and human-light — is what compounds an edge over time, more than any single AI model’s raw quality. He explicitly sees this trending toward humans being largely out of the loop within a few years.
These structural predictions are great. But you fundamentally need to test these predictions in a lab. And here is the Biggest insight in this article
”Let AI design, plan and conduct its own experiments, sort of like Tool calling” in order to reach the drug discovery goal you gave them”. Hear the insight directly below
I think that AI models can design new experimental protocols and receive feedback, achieving about 80-90% zero-shot success on expression protocols, indicating strong autonomous scientific reasoning.The same intuition is now being applied by many startups like Chai Discovery (Raised $400M) or Lila AI (Raised $550M)
INSIGHT 5
Toxicity/off-target effects — not efficacy — is the industry’s real gatekeeper. Drug dropout comes down to two questions:
Does it work, and is it toxic.
AI has made real progress on the first; almost none on the second. The ideal fix — screening a candidate in silico against every other protein in the body to catch unintended interactions — is “computationally hard” and still mostly aspirational, not solved.
This is the reason AI is limited to discovery for now. There are simulations, but its still a few years away. I am writing a part 2 on this for beneficiaries of this particular insight.
INSIGHT 6
A “design-plus-royalty” business model is emerging, borrowed from chip design. Get paid up front for design/service work, then take a profit-share/royalty if what you designed succeeds downstream (echoes how chip design houses get paid at tape-out, then earn more on yield). I think that Drug discovery process is exactly the same process as ASIC chip design. I will expand on this in PART 2
RISKS
AI can design the molecule, but AI cannot make the FDA skip the part where you prove its safe and it works, - in actual humans over actual years.
AI helps by raising the odds that the molecule survives the test by dramatically dropping the odds of dropout rates.
We might be early in industry really appreciating these insights
Before we move on, special shoutout to Sam for helping me reach these insights. He has just started a substack and here is his first post.

Okay so now that we understand the basic insights, lets cover the two stocks that are poised to benefit from all this. Unfortunately a lot of the value creation is happening in private with VC money, however there are some investing options available to us
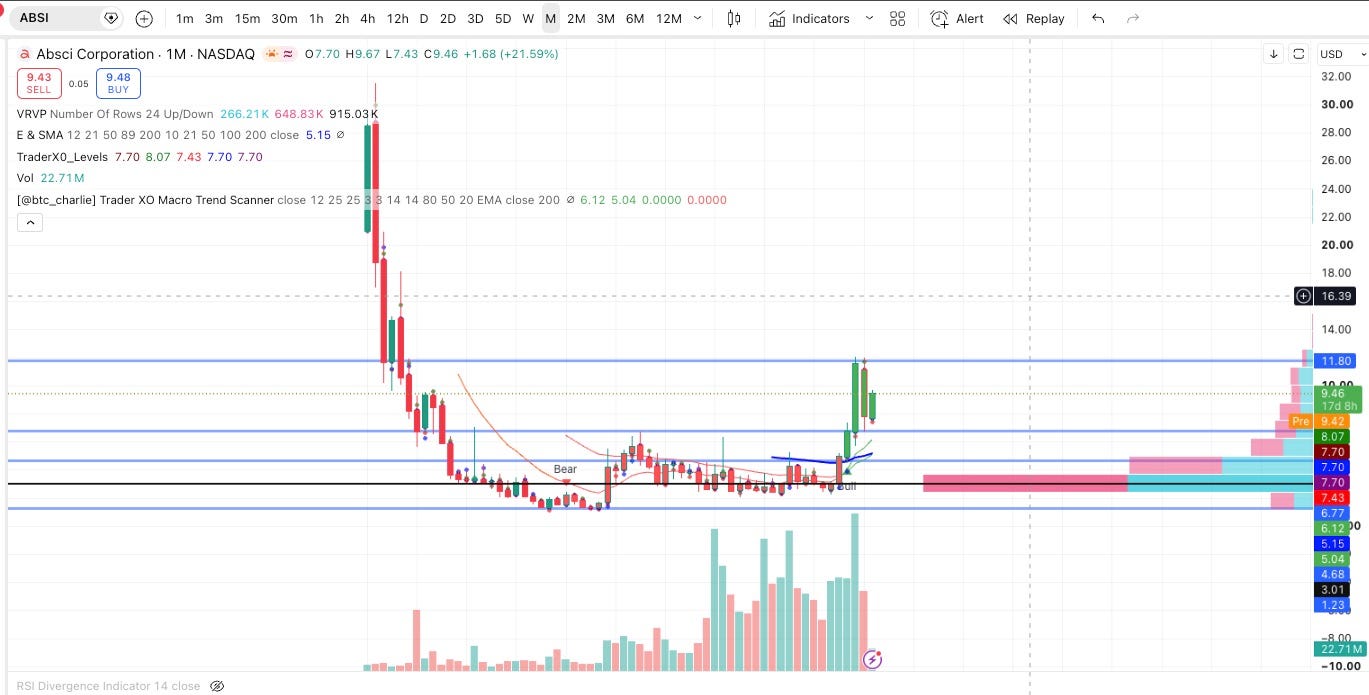
ABSI ($1.6B Market cap)
They got a great first slide. Summarizing our insights
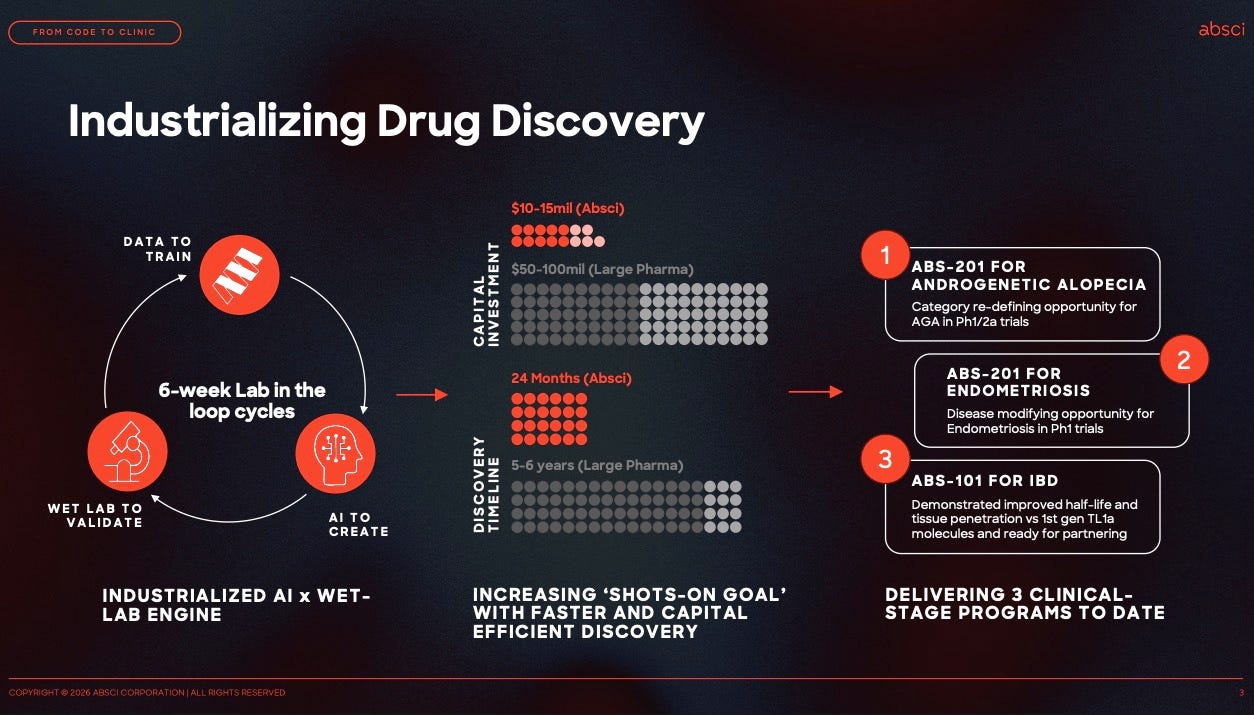
Absci is the first validated platform to de novo design full length antibodies against ‘zero-prior’ epitopes with atomic accuracy
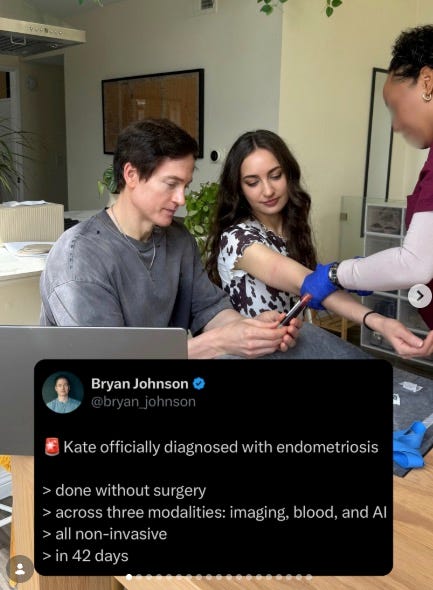
I am particularly excited about their cure for Endometriosis. 10% of women worldwide face this disease and there is simply no cure. Bryan Johnson’s partner/founder Kate recently announced that she got it
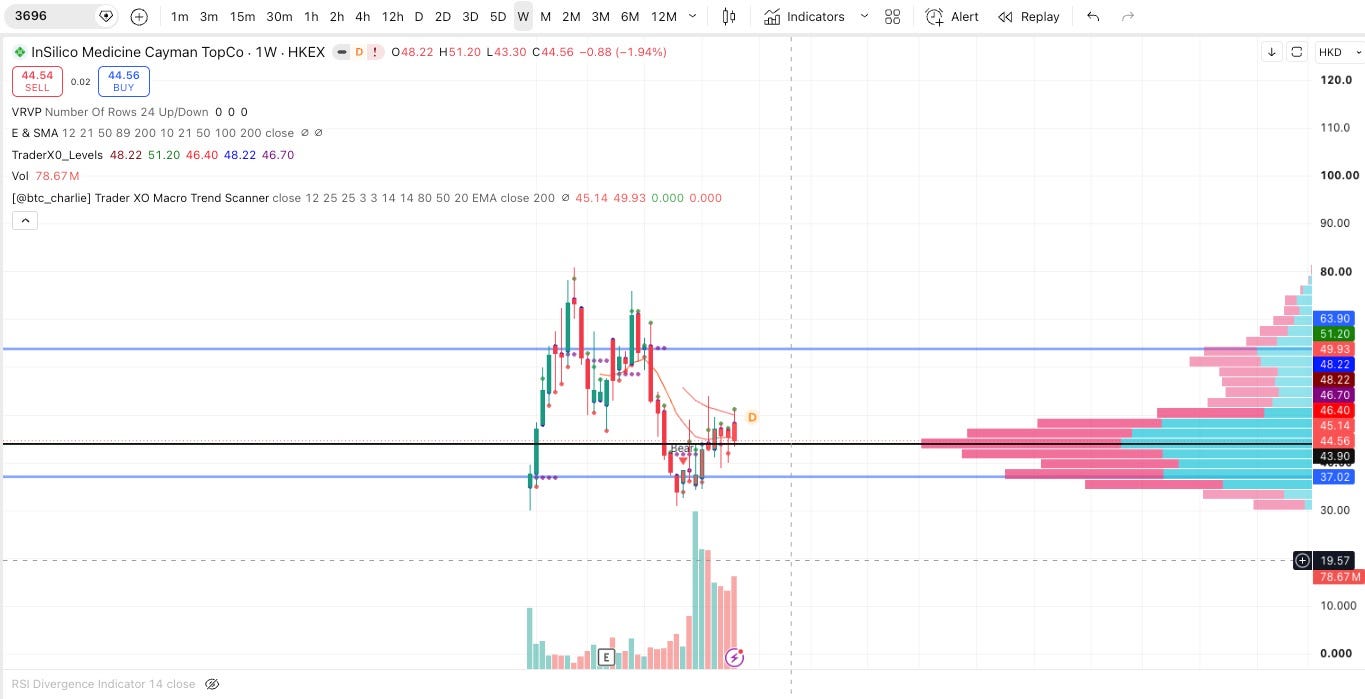
INSILICO ($3696 Hong Kong based ±$2B Market cap)
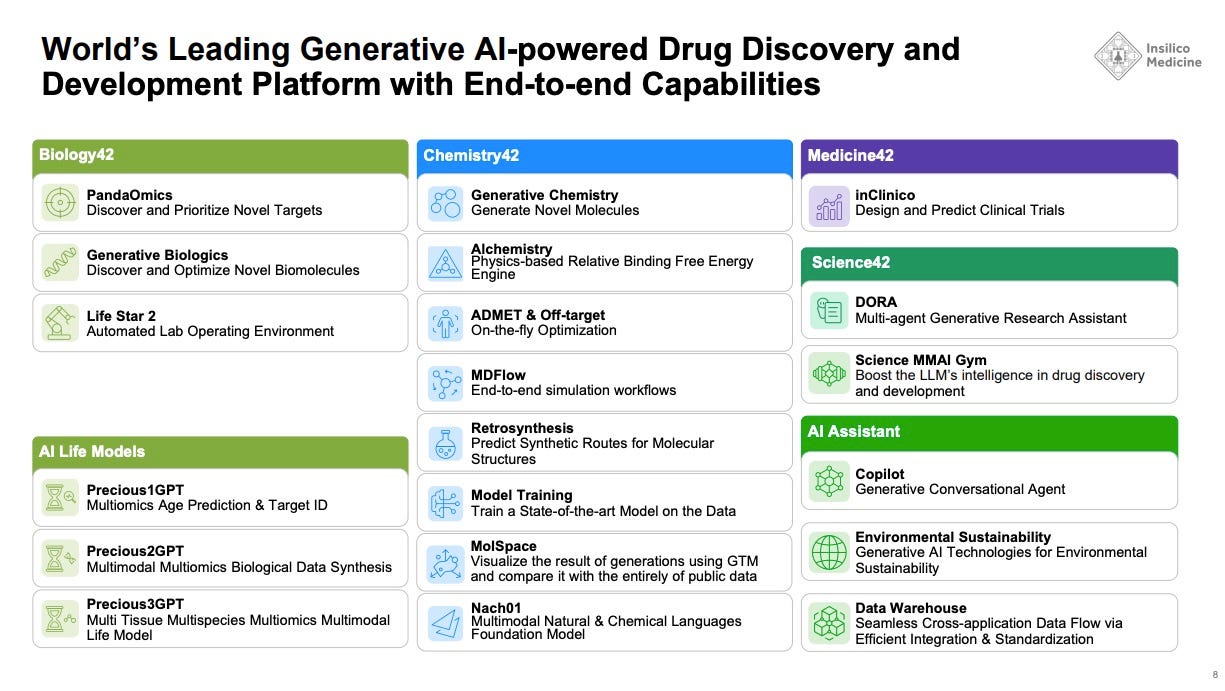
AI-first, closed-loop pharma — not a bolt-on: PandaOmics (AI target-finder) finds the disease target, generative AI designs the molecule, then an in-house automated robot lab tests and iterates. Full stack, no legacy.
Real clinical signal, not noise — their pulmonary fibrosis drug reverses the disease indicator in Chinese trials, while the two existing approved drugs only slow it. Sam said that the odds of that being a false signal are “vanishingly low.”
Big catalyst incoming — the larger US FDA trial readout is due ~summer 2026. The important thing to know is that Chinese phase 2 was already found to be successful. No reason why US FDA would fail.
~$2B market cap (HK-listed, ~572M shares) is arguably low if this scales. It is not hard to be a $50-$100B company.
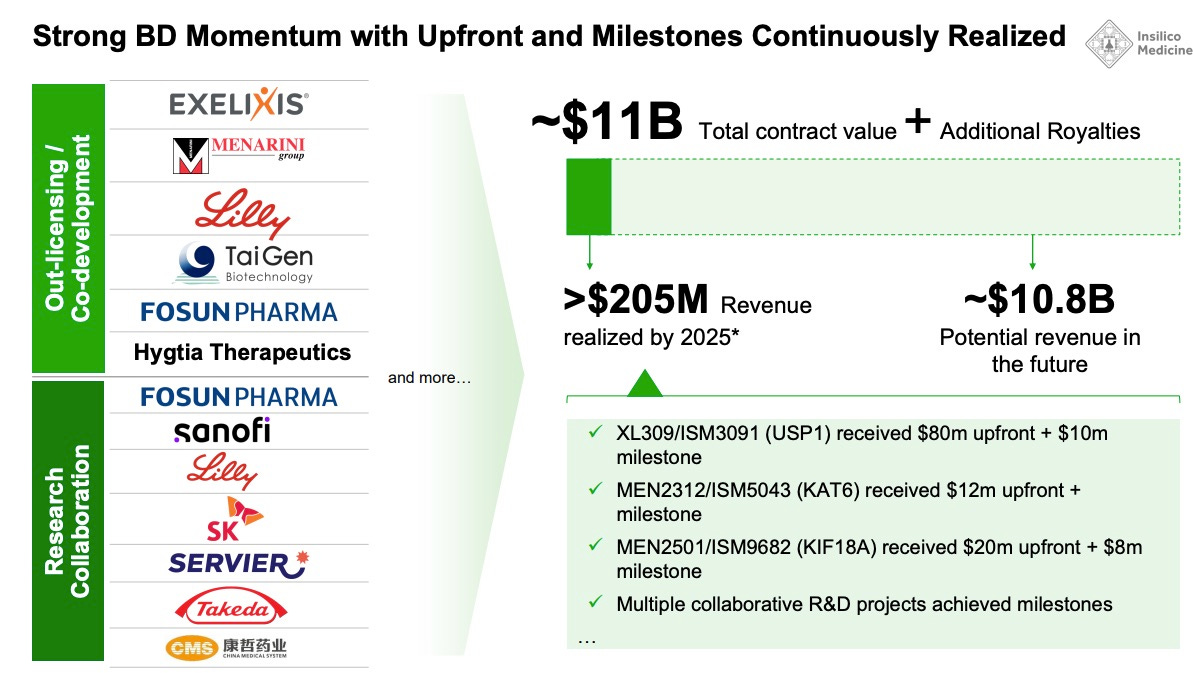
Especially because they are allowing renting their AI wet labs and will keep a revenue share. So any drug that works on their platform, will have to pay them royalties
Founders delayed their stock unlocks by a year so summer 2027
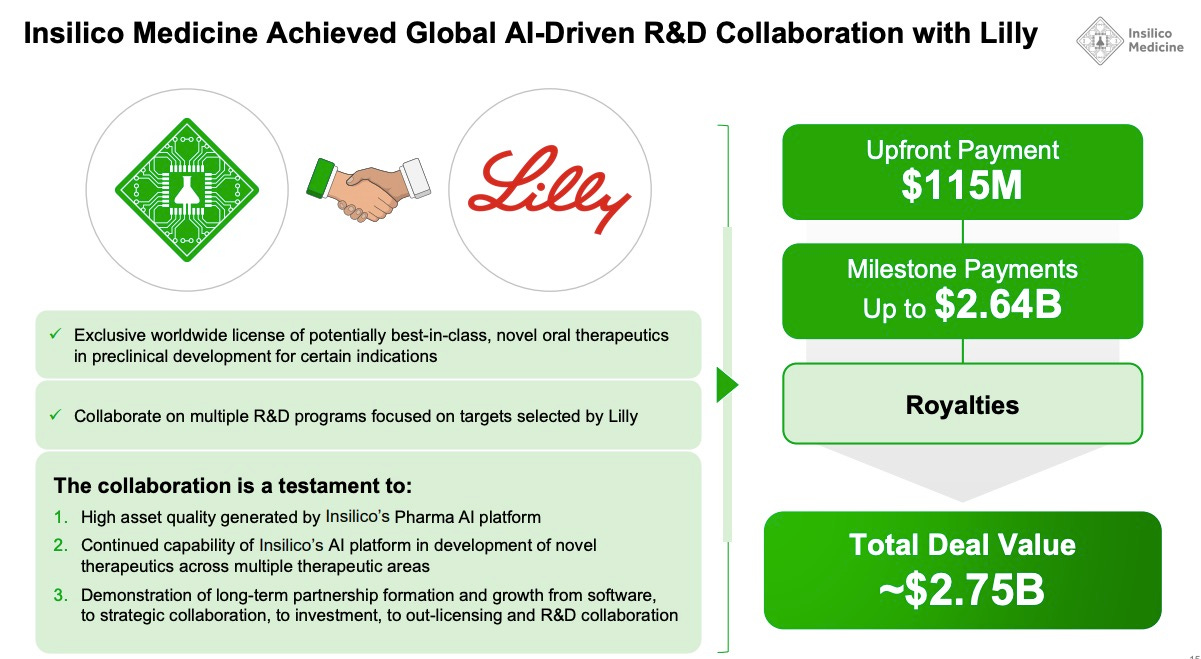
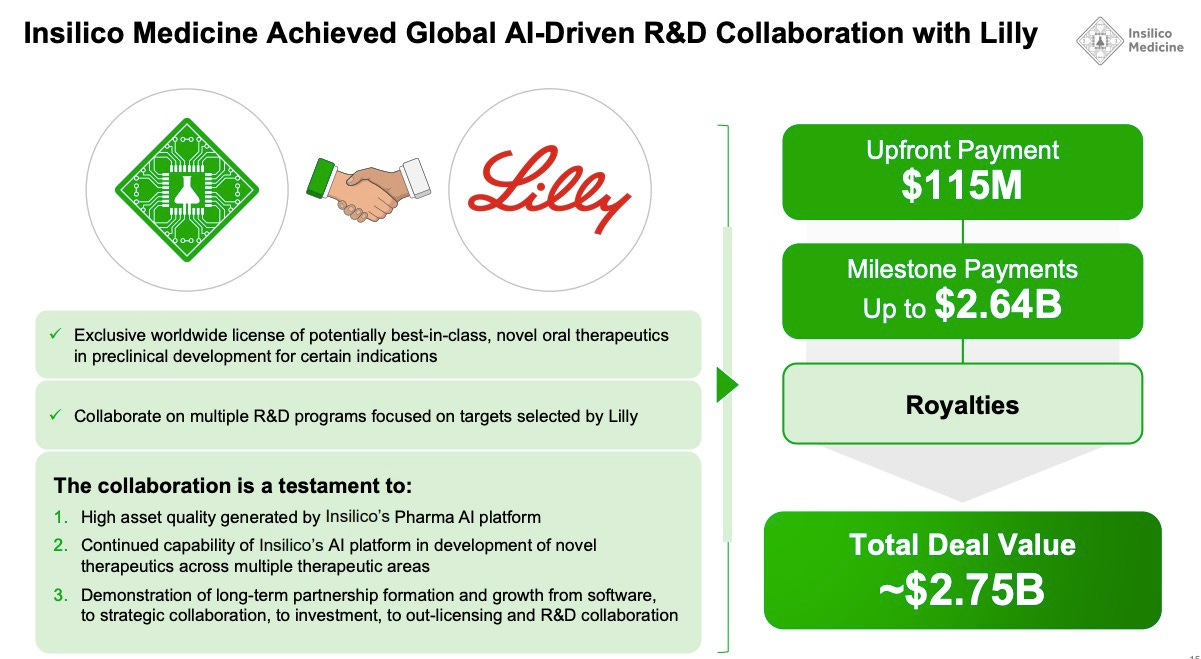
Backed by Eli Lilly. They already got ~$115M upfront payment with a chance to get to $2.75B
Cayman-incorporated, non-Chinese CEO but Chinese leadership elsewhere, which may be why the US listing didn’t happen — still an open research thread.
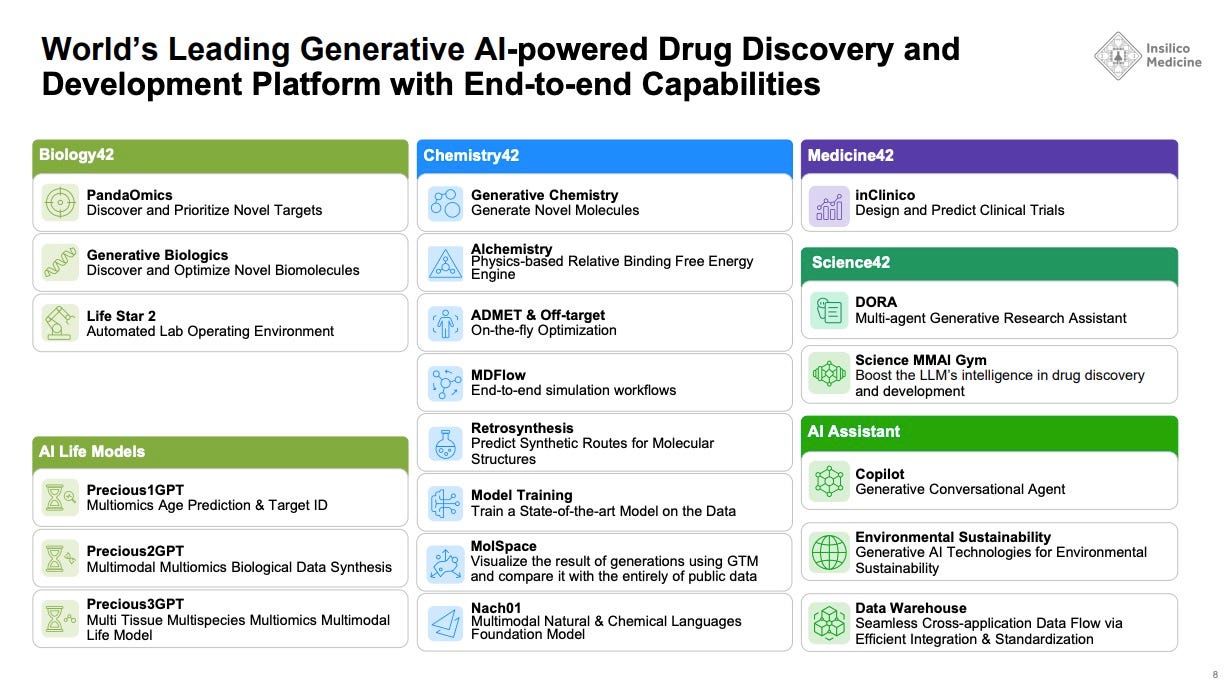
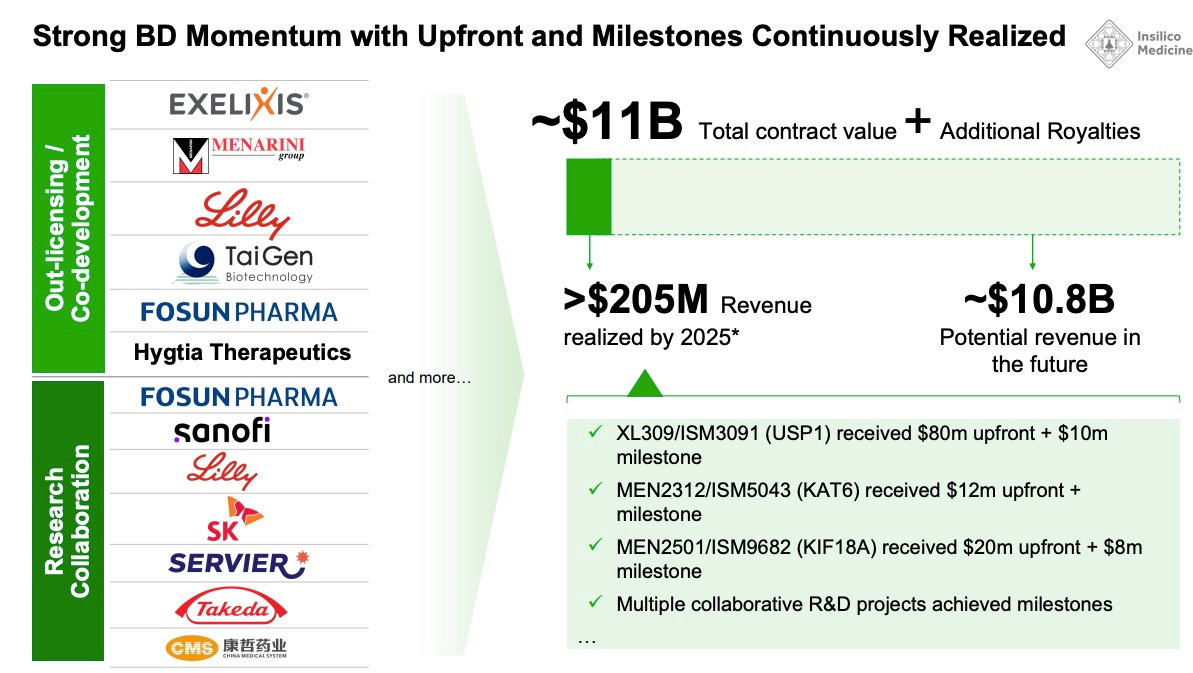
So watch the numbers that count. Insilico has spun out 200-plus molecules per program, several already at IND, in 12 to 18 months from target to candidate — against the old industry clock of 4 to 6 years.
The age of expensive failure is closing, and the age of designed medicine is opening. That’s the trade.
Stay Tuned for Part 2